


Storm, Fire, or Flood With an Open HELOC: Insurance Checks, Credit Line Freezes, and Rebuilding in 2026


 FACT-CHECKEDFACT-CHECKED
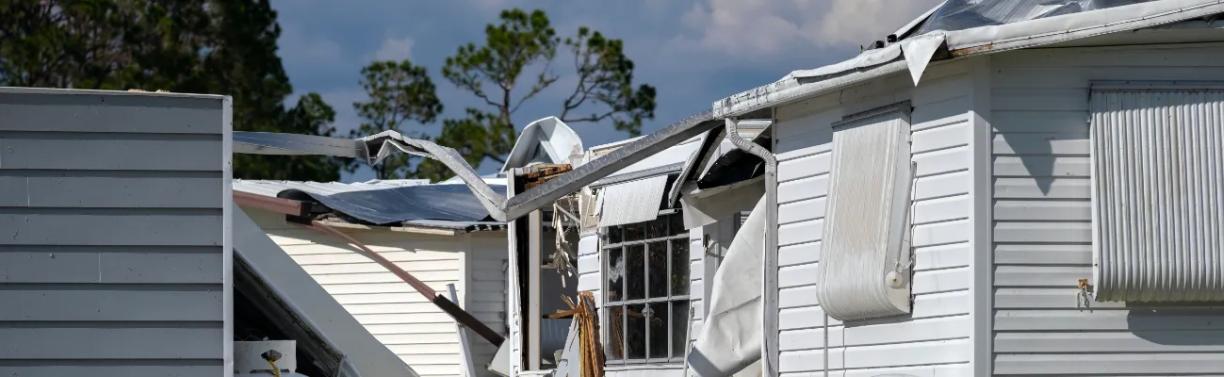
After a storm, fire, or flood, the house takes the damage and the loans on it keep running as written. Your insurer, your first-mortgage servicer, and your HELOC lender each hold a different piece of the recovery, and each one waits for you to start the conversation. This is the order to make those calls in, and the words to use.
Key Takeaways
- Damage to the house doesn't pause the first mortgage or the HELOC; both keep billing on the original terms.
- Regulation Z lets a HELOC lender freeze new draws when the home's value declines significantly, even if you're current.
- Insurance settlement checks generally name you and your mortgage servicer, and repair funds are released in stages.
- Work the insurer first, the first-mortgage servicer second, and the HELOC lender third, as three separate conversations.
- Ask for reinstatement of a frozen line in writing as soon as repairs restore the home's value.


What Happens to a HELOC on a Damaged House
Start with the part that doesn't change. A storm, a fire, or a flood does its work on the structure, and the loans recorded against that structure keep running on the terms you signed. The CFPB says it in one sentence in its disaster guidance: damage to your home doesn't stop your responsibility to pay your mortgage, though there may be options to help you. That obligation runs through the claim itself: if you have a mortgage, you're still responsible for making your payments while your insurance claim is paid out.
A home equity line of credit sits on the same property under a separate contract, with its own servicer and its own rulebook. The balance you drew before the disaster is still drawn, interest keeps accruing on it, and the monthly payment keeps coming due. The undrawn part of the line, the availability you may have been counting on for a deductible or for the gap between the adjuster's number and the contractor's bid, can be suspended for reasons that have nothing to do with your payment history.
I've been in this industry since my first job out of college, and for years now I've run the operations side at AmeriSave, where files arrive in whatever condition life left them. A disaster file has a recognizable shape: the payment history is usually clean, the house has changed, and you're trying to reach three institutions in the same week, often from a hotel or a relative's spare room. I grew up in a small town on Florida's Gulf Coast, so storm season was a fact of the calendar for me.
Three institutions is the number to hold onto. Your insurer decides how much money exists and whose names go on the check. Your first-mortgage servicer usually controls when that money gets released for repairs, and it's also the desk where relief on your monthly payment lives. Your HELOC lender decides whether your credit line stays open while the house is damaged. None of the three coordinates with the others; your mortgage and your home equity loan are separate creditor accounts, and each creditor needs to hear from you as soon as possible after a disaster. In production terms, you're the only person who can see all three files at once.

Why a HELOC Gets Frozen After Home Damage
A suspension letter can arrive even if you've never missed a payment, because the condition behind it is the value of the collateral, and the letter should name that condition.
Regulation Z, the CFPB rule that governs home equity plans, permits a lender to prohibit additional extensions of credit or reduce the credit limit during any period in which certain conditions exist. Six conditions are listed, and the first is the one a disaster triggers: the value of the dwelling that secures the plan declines significantly below the dwelling's appraised value for purposes of the plan. A roof that's gone or a first floor that took on water drops the collateral below the number the lender used when it opened the line, and the rule asks nothing more than that.
Other listed conditions, such as a material change in your financial circumstances that makes the lender reasonably believe you won't be able to meet the repayment obligations, or a default on a material obligation under the plan, involve your finances and your conduct. The property condition involves the house, so a lender can freeze the line while you're current on every payment you've ever made.
The word "significantly" comes with no number attached. Regulation Z sets no percentage and no dollar threshold for a significant decline; it's the lender's judgment applied to the facts of the property. In plainer terms, the lender may prohibit further advances or reduce your limit if the value of your home decreases significantly, and may separately freeze your ability to draw if your financial circumstances change in a way that threatens repayment. A valuation problem is fixed with a valuation. A financial-circumstances problem is fixed with documentation of your income, credit, and assets.
The standard I hold our teams to at AmeriSave when any file slows down is to name the reason first, and the same standard applies to a freeze letter: you're owed the specific condition the lender relied on, because the remedy depends on it. The regulation also ties the freeze to the period in which the condition exists, so a freeze that started when the house lost value has a natural end point, which is the house getting its value back.
The Insurance Check Has More Than One Name on It
The first real money after a disaster is the settlement check, and the payee line is where the process first slows down. The CFPB explains the reason: your homeowner's insurance company generally pays a covered settlement with a check made out to both you and your mortgage servicer or lender, because most mortgage agreements require it to protect the lender's interest in the property, and the servicer may need to approve or endorse the check before you can cash it. That's a term you agreed to at closing.
If you have a HELOC on the same property, that lender also holds a recorded interest in it. Whether your insurer names the HELOC lender on the settlement paperwork depends on your policy and on what the insurer's file shows, so ask rather than assume. If you have more than one loan against the house, expect to deal with each lender separately about the claim, and ask the insurer up front, before anyone signs anything, exactly whose names will appear on the settlement.
For a covered loss above the servicer's own threshold, the servicer typically releases a portion of the settlement before work begins so you can hire a contractor, releases more as the work progresses, and releases the remainder once the job is finished and the home passes inspection. Staged release is the default design, which is why your contractor's payment schedule has to be built around the servicer's release schedule.
The specifics depend on who owns your loan. If your first mortgage is owned by Fannie Mae, its Servicing Guide spells out the mechanics. The servicer is required to file a proof of loss under the standard mortgagee clause and collect the insurance proceeds if you haven't done so yourself. For a loan that's current or only slightly behind, the servicer may release an initial disbursement of up to the greater of $40,000 or 33% of the proceeds, with the rest disbursed based on periodic inspections of the repair work. A loan that's 31 or more days delinquent gets smaller, tighter releases, which I'll show in the worked example, and claims of $5,000 or less can be paid in a single disbursement. Other investors and portfolio lenders run their own schedules, so ask your servicer which one applies to your loan. Those rules cover the first mortgage only; your HELOC lender sets its own requirements for the claim, which is one more reason it gets its own call.

The Order That Works: Insurer, First-Mortgage Servicer, Then HELOC Lender
Each of these conversations depends on something the previous one produced, which is why sequence beats speed. The failure I see most often, and the one I'd probably commit myself in the first forty-eight hours if I weren't in this business, is calling all three on the same afternoon. Everything then stalls because the servicer wants an endorsed check the insurer hasn't issued yet and the HELOC lender wants a valuation nobody has ordered. Run the calls in order and each one hands you what the next one needs.
First, the Insurer and the Payee Question
Start the claim from wherever you're staying, whether or not you can safely reach the property yet; the call to your servicer about disaster relief comes right behind it. Get the adjuster scheduled, then ask, in these words: "Who will be named as payees on the settlement check?" and "If the contractor finds more damage once the walls are open, can I file a supplemental claim, or does signing this settlement close the file?" The first answer tells you how many lenders you're coordinating. The second protects you if the damage runs deeper than the first walkthrough showed.
Second, the First-Mortgage Servicer, for the Funds and the Payment Together
Call the servicer once the claim is open and you know how the check will be issued. Start with the settlement: how the servicer wants the check endorsed, what documentation it needs before the initial release, how it schedules inspections, and how long a release takes after an inspection clears. Ask for that list in writing and hand it to your contractor before the contract is signed. Then turn to your payment and put the question to your servicer directly: "What options are available to help me temporarily reduce or suspend my payments? Are there forbearance options?" Ask it on the same call, because the settlement desk and the hardship desk may be different departments.
Third, the HELOC Lender, as Its Own Conversation
Nothing from the first two calls reaches your HELOC on its own. It's a separate account, frequently at a separate company, and the servicer on your first mortgage isn't in the business of updating your other creditors. Call the HELOC lender and ask three questions: "Has my line been suspended or reduced, and if so, under which condition in my agreement?" "What are my payment options on this account while the property is being repaired?" and "What documentation will you accept to reinstate the line once repairs are complete?" That opening answer settles whether you're fixing a valuation or fixing a file, and the third puts the reinstatement standard in your hands months before you need it. Two loans on one address are still two loans, whether both are with AmeriSave or with two lenders who've never spoken, and I'd rather you hear it now than discover it standing in a gutted kitchen.
Mortgage Forbearance After a Hurricane, and Whether It Reaches the HELOC
Forbearance is the word you'll hear most in the weeks after a declared disaster. It means a servicer agreeing to let you temporarily reduce or suspend your payments. The amount you didn't pay is still owed, and how you make it up is set by the agreement you sign, so finish that conversation before the pause starts.
Forbearance is requested, and the request comes from you. It's a question you put to your servicer, and the servicer is the one who tells you what relief it offers. A disaster declaration covering your county tells your servicer nothing about your particular house, your living situation, or your income; your call is what moves your file into the relief queue.
Make the request specific and make it early. Say it this way: "My property was damaged in the disaster, I'm requesting forbearance or another hardship option on this account, and I'd like the terms in writing." In my experience, a request that arrives early with a claim number attached is easier to act on than one that arrives after a missed payment, because the file has a documented reason before it has a delinquency.
Relief on the first mortgage stays on the first mortgage. There's no federal forbearance program for HELOCs, so treat HELOC hardship options as the lender's to offer and the answer as a negotiation rather than an entitlement. If the lender agrees to reduce or pause your payment, get the agreement in writing before you rely on it. If it doesn't, the HELOC payment stays due through the rebuild and needs a line in your recovery budget. Government-backed first mortgages carry their own disaster rules. If your loan is in one of those programs, ask your servicer what it requires.
A Worked Example: A $120,000 Claim With a $40,000 HELOC Balance
Run a hypothetical with me. Say a fire causes $120,000 in covered damage to a house carrying a first mortgage owned by Fannie Mae and a HELOC with $40,000 drawn against it. The rebuild takes eight months from the adjuster's visit to the final inspection. Every figure below is illustrative and depends on these assumptions.
The insurer issues a $120,000 settlement made out to you and your first-mortgage servicer. After both endorsements, the money sits with the servicer for the repair. If the loan is current, the Fannie Mae schedule allows an initial release of up to the greater of $40,000 or 33% of the proceeds, and since 33% of $120,000 is $39,600, the $40,000 figure is the ceiling on the first release. The remaining $80,000 comes out in pieces as inspections confirm progress, which on an eight-month job means several inspection cycles, each with its own turn time.
Now change one fact. Say the first mortgage was 31 days past due when the fire happened. For a loan that's 31 or more days delinquent, the Fannie Mae guide limits the initial release to 25% of the proceeds and no more than $10,000, unless the proceeds exceed what's owed on the loan, with later releases in increments of no more than 25%, each tied to an inspection. On $120,000 that's a $10,000 start and then disbursements of no more than $30,000 each. Same house and same damage, with slower money. That's the operational reason to keep the first mortgage current if you possibly can, or to get a forbearance agreement in place before a payment is missed.
Meanwhile, the HELOC bills every month. Most variable-rate HELOCs price off the bank prime loan rate plus a margin the lender sets, and the Federal Reserve's most recent H.15 release puts prime at 7.00%. At the index alone, with no margin, $40,000 costs about $233 a month in interest ($40,000 times 7.00%, divided by 12), so eight months of rebuilding runs roughly $1,870 in interest. Your actual rate includes your margin, so your actual number is higher; in this example, each additional percentage point of margin adds about $33 a month.
Now add the freeze. If the HELOC lender suspends new draws the week after the fire, the $40,000 you already drew stays drawn and stays billable, and the availability above it disappears until the collateral recovers. This is the specific squeeze a disaster creates when you have an open line: a balance that keeps accruing beside availability that stopped existing.
Rebuilding After a Disaster With a HELOC: Getting the Line Reinstated
If the freeze was triggered by the property's value, the reinstatement decision rule is short. Ask in writing, ask as soon as the repairs restore the value, and don't wait for the lender to notice on its own.
Regulation Z permits the freeze during any period in which the value has declined significantly below the appraised value used for the plan. A finished rebuild changes that fact, and your lender learns about it when you tell it. In production terms, a reinstatement request is a re-underwrite of the collateral, and it moves at the speed of the documentation you put in front of the lender. The requests that clear fastest arrive as one complete package: the final inspection report, the certificate of completion or permit sign-off, photographs, and a written request that names the account number, states the date repairs were completed, and asks for the line to be restored to its original limit.
On the operations side we describe our work as turning documents into data, and a reinstatement package is your version of the same idea. Where this usually goes wrong is patience pointed in the wrong direction: the rebuild finishes, the file sits, and the freeze is still in place months later when the line is needed again. The alternative costs one letter. Send the package the week the final inspection clears, keep a copy, and follow up in writing if you haven't received a decision within the time frame the lender gave you. If the lender declines, ask which listed condition it believes still exists, because each one has its own remedy. That's the same discipline that decides turn times on every file we touch at AmeriSave, and it's the one part of this process where you set the pace.
The Tax Side: HELOC Interest, Insurance Money, and Casualty Losses
Interest on HELOC draws used for the rebuild is deductible under IRS Publication 936 only to the extent the proceeds were used to buy, build, or substantially improve the home that secures the line. Publication 936 says an improvement is substantial when it adds value, prolongs the home's useful life, or adapts it to new uses, so rebuilding or upgrading after a disaster can qualify while work that only restores the home to its prior condition may not. The deduction is capped at the first $750,000 of combined acquisition debt ($375,000 if you're married filing separately) for debt taken on under the current rules, so keep the draw records separated by purpose.
On what insurance didn't cover, IRS Publication 547 allows a casualty loss on your home only if the loss is attributable to a federally declared disaster, and any insurance reimbursement you received or expect to receive reduces that loss dollar for dollar. This describes how the IRS rules work rather than advising on your return, so have a tax professional who can see your whole picture run the numbers.
The Bottom Line
Three institutions, one order. Open the claim with your insurer and settle the payee question before anyone signs a check. Call your first-mortgage servicer next and put the settlement and your payment into the same conversation. Then give your HELOC lender its own call, lead with whether the line is open, and get the reinstatement standard in writing while the freeze is fresh.
In operations we run on a principle that ends up written on whiteboards: do the hard things first. After a disaster the hard thing is almost always the call you'd rather put off, usually the one to the lender holding the frozen line, because that conversation has no good news in it yet. Make it anyway, and make it early. Every week it waits is another week of interest at the same rate on the same balance.
The weather, the adjuster's calendar, and the lender's valuation are outside your hands. The order of your calls and the paper trail you leave are inside them. At AmeriSave, the standard we try to hold ourselves to on any file that's slowed down is a plain explanation of where it stands and what moves it next. After a disaster, that explanation is the thing to insist on from every institution you're working with, and the sequence in this piece is how you get in front of the people who can move your file.
Consumer Financial Protection Bureau. What do I do if my house was damaged or destroyed, or if I'm unable to make my payment after a disaster?
Consumer Financial Protection Bureau. How do home insurance companies pay out claims?
Consumer Financial Protection Bureau. What should I do after a disaster to protect my finances and property?
Consumer Financial Protection Bureau. What is a home equity line of credit (HELOC)?
Consumer Financial Protection Bureau. Your Disaster Checklist.
Legal Information Institute, Cornell Law School. 12 CFR 1026.40, Requirements for home equity plans.
Fannie Mae. Servicing Guide B-5-01, Insured Loss Events.
Internal Revenue Service. Publication 547, Casualties, Disasters, and Thefts.
Internal Revenue Service. Publication 936, Home Mortgage Interest Deduction.
Board of Governors of the Federal Reserve System. H.15 Selected Interest Rates.

Mike brings over a decade of mortgage operations experience to AmeriSave, starting in Applied American Politics before transitioning to mortgages in 2008. He holds a Bachelor's in Finance from Florida State University and Google certifications in Digital Sales and Ads. Based in Louisville, KY with his wife and three children, he specializes in operational excellence and making the mortgage process accessible and efficient for everyday borrowers.
Frequently Asked Questions
Yes. Regulation Z permits a HELOC lender to prohibit additional draws or reduce your credit limit during any period in which the value of the home securing the plan has declined significantly below the appraised value used for the plan, and storm, fire, and flood damage all reduce that value. The regulation sets no percentage or dollar threshold for "significantly," so the decision is the lender's judgment about the property, and a clean payment history doesn't prevent it.
Because most mortgage agreements require it. The CFPB explains that your homeowner's insurance company generally pays a covered settlement with a check made out to both you and your mortgage servicer or lender, to protect the lender's interest in the property, and the servicer may need to endorse the check before you can cash it. If you also have a HELOC, that lender holds a recorded interest in the home too, so ask your insurer before signing anything exactly whose names will appear on the settlement.
The balance stays owed and the terms stay as written, so the amount you drew before the disaster keeps accruing interest and the monthly payment keeps coming due while the rebuild runs. What can change is your access to the undrawn portion of the line, since Regulation Z lets the lender suspend new draws or cut the limit while the home's value sits significantly below its appraised value for the plan. Call that lender directly, confirm whether the line is open, and ask what reinstatement will require once repairs are done.
No. Forbearance is relief you request from a specific servicer on a specific account, and an agreement on your first mortgage doesn't extend to a HELOC held under a separate contract, often at a separate company. HELOC hardship options are the lender's to offer, so call that lender separately, ask what it can do on the account during repairs, and get any arrangement in writing before you rely on it.
Ask in writing as soon as the repairs restore the home's value, and send the request as one complete package: the final inspection report, the completion or permit sign-off, photographs, your account number, the completion date, and a request to restore the original limit. Regulation Z permits the freeze only during the period in which the value decline exists, but the lender won't know the work is done until you tell it. Ask at the time of the freeze what valuation evidence the lender will accept, since it may want a new appraisal before it acts.
It can be, with conditions. IRS Publication 936 allows the deduction only to the extent the HELOC proceeds were used to buy, build, or substantially improve the home that secures the line. A substantial improvement adds value, prolongs useful life, or adapts the home to new uses, so a rebuild or upgrade after a disaster can fit while work that only restores what was there may not. The deduction is limited to the first $750,000 of combined acquisition debt ($375,000 if you're married filing separately) for debt under the current rules. This describes the IRS rules rather than advising on your return, so confirm your situation with a tax professional.