


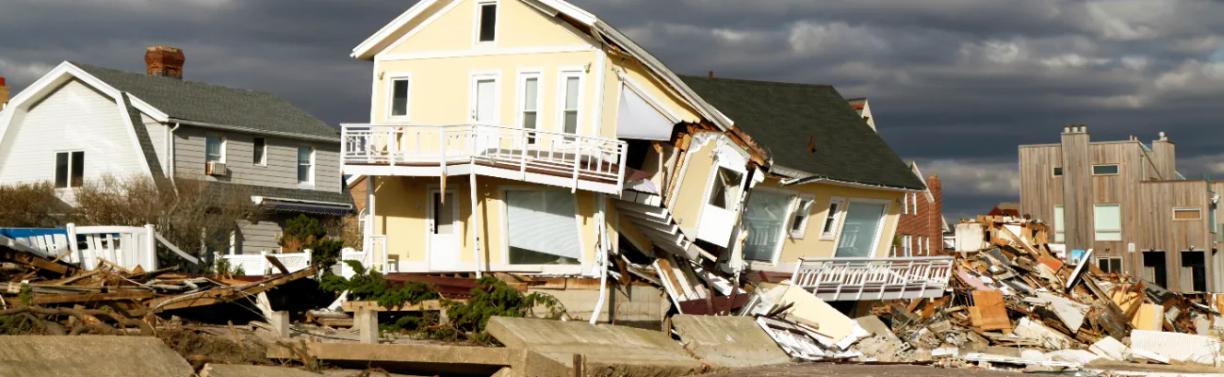
SBA Disaster Loans vs. Home Equity in 2026: Paying for Repairs Insurance Won't Cover


 FACT-CHECKEDFACT-CHECKED
When insurance leaves a gap after a storm, repairs can't wait on slow money. An SBA home disaster loan is the cheaper option and home equity is the faster one, so the plan that holds up uses both in order. I'll walk through how each works, what a $60,000 roof costs three ways, and why you apply for both on day one.
Key Takeaways
- SBA home disaster loans cap at 4% if SBA finds you can't get credit elsewhere, 8% if it finds you can, and fund slowly.
- Home equity closes faster at a higher cost, which makes it the right tool for the first months of repairs.
- The plan that holds up: draw on your equity now, then let the SBA loan pay that balance down once it funds.
- Apply for both on day one, because an SBA declination is also what opens the door to FEMA's Other Needs Assistance.
- Above $50,000 in a Presidential declaration, SBA asks for collateral, so tell each lender about the other lien.


The Short Answer: Use Both, in the Right Order
I've spent 26 years in the mortgage business, and my family spends time in Florida most years, so storm season has my attention every year. The question that follows a bad one is always some version of the same thing. The adjuster's number came in low, or the claim was denied outright, and the roof is open. How do you pay for repairs the insurance company won't cover?
The shortest version is this. The SBA home disaster loan is the cheapest money you'll find for uninsured repairs, and it's slow. Home equity, whether a home equity loan or a HELOC, is faster, and it costs more. Put those two facts together and you get one plan: open the equity line now and start the repairs, then let the SBA loan pay that balance down once it funds. The rest of this article explains why that order works, what it costs on a real repair bill, and where it can trip you up.
One more thing before the details. I'm cautious about anyone who tells you exactly how long a government loan program takes after a disaster, and I'm going to hold myself to the same rule. SBA's process includes a property inspection and an underwriting review before money moves, and the clock depends on the disaster and the caseload behind it. I'll describe the sequence and the costs. I won't invent a day count.

Why Insurance Leaves a Gap in the First Place
Life happens, and after a storm it happens all at once. The gap between your repair estimate and your insurance check usually comes from one of four places.
- A hurricane or windstorm deductible set as a percentage of your dwelling coverage, so the first slice of a large claim is yours before the insurer pays anything.
- Flood damage, which a standard homeowners policy doesn't cover. Flood coverage is a separate policy, and without one the water damage is on you.
- A wind-versus-water dispute over what caused what, which leaves claims partially paid or denied while the appeal runs.
- A claim approved in full, with a check that still arrives on the insurer's schedule while contractors and supply yards run on theirs.
Every one of those paths ends at the same place: a repair bill with no insurance money behind it and a house that gets worse every week it sits open. Before you borrow a dollar to close that gap, I'd want you comfortable with two things, the same two I'd want any loan officer on our team at AmeriSave to put in front of you. How fast does the money arrive, and what does it cost once it does? With these two loans, those questions pull in opposite directions, and that's the whole reason the order matters.
How the SBA Home Disaster Loan Works
The Small Business Administration runs the federal government's disaster loan program. Despite the name, you don't need to own a business to use it. FEMA's own guidance on the program says so directly: homeowners and renters apply to SBA for disaster loans, and the usual path in is a referral from FEMA after you register for disaster assistance.
The program is tied to a disaster declaration, either a Presidential declaration or an administrative declaration by SBA itself, so the first thing to confirm is that your county is covered. Once it is, five things about the loan matter for the plan in this article: how much you can borrow, what it costs, what SBA takes as collateral, how FEMA fits around it, and how long it takes.
How Much You Can Borrow
SBA's physical damage loan page sets the limits. As a homeowner you can borrow up to $500,000 to repair or replace your primary residence, and up to $100,000 to repair or replace personal property, meaning clothing, furniture, cars, and appliances. For a repair bill like the $60,000 example later in this article, the cap is a long way off. The number that does the deciding is SBA's own inspection. SBA sizes the loan to the loss it verifies, so have your contractor's estimate and photos organized before the inspector arrives.
What It Costs
This is where SBA wins, and it's written into federal regulation rather than a rate sheet. Under 13 CFR 123.104, the fixed rate on a home disaster loan won't exceed 4% a year if SBA determines you can't get credit elsewhere, and won't exceed 8% a year if SBA determines you can. "Credit elsewhere" is SBA's judgment about whether you could borrow the money from non-federal sources on reasonable terms. Both numbers are ceilings. SBA sets the actual rate at or under them, and the determination is SBA's to make, so ask your SBA loan specialist how the equity in your home factors into it.
Three more terms from SBA's program page shape the math. The loan can run as long as 30 years. Your first payment is deferred for 12 months, and no interest accrues during that deferral. And there's no prepayment penalty, so paying it off early costs you nothing extra.
Run that on the $60,000 repair I'll use throughout. At the 4% ceiling over 30 years, the payment comes to about $286 a month. At the 8% ceiling, about $440 a month. Either way, year one costs you nothing, and the interest clock doesn't start until the deferral ends. I've been in this business a long time, and I don't know of another way to borrow $60,000 against a house on those terms.
The Collateral Rule and the Lien
SBA's program page is clear about collateral. For physical damage loans above $50,000 in a Presidentially declared disaster, and above $14,000 in an SBA administrative declaration, SBA requires collateral to the extent it's available, and it prefers real estate. The same page says SBA won't decline a loan solely because you lack collateral. In plain terms, a $60,000 home repair loan clears the threshold, so expect SBA to ask for a lien on your house.
That lien takes whatever position is open behind your existing mortgage and behind any equity line you've already put on the property. This is the detail the whole plan hangs on. SBA's lien and your equity lender's lien have to coexist on the same house, and both lenders need to know about each other before either one closes. I'll come back to how you handle that conversation.

Where FEMA Fits
FEMA and SBA run as a pair. You register with FEMA for disaster assistance, and FEMA may refer you to SBA for a loan. What happens next is spelled out in a FEMA fact sheet that I'd want every homeowner in a declared area to read. Complete and submit the SBA application even if you expect to be denied, and even if you don't want the loan. If SBA declines you, SBA refers you back to FEMA, and you may then be eligible for additional grant assistance under FEMA's Other Needs Assistance program for things like personal property and transportation. If SBA approves you, FEMA's guidance is equally direct: you're not required to accept the loan.
That's why the SBA application is the first form you fill out. Filing it keeps every option open, and you can still say no to the loan.
What Slow Means Here
I said I wouldn't put a day count on SBA, and I'll keep that promise. What I can describe is the sequence. After you apply, SBA inspects the damage, reviews your credit and your ability to repay, decides the credit-elsewhere question, and then documents the collateral. Money moves after all of that. Each step is reasonable on its own. Together they take longer than a homeowner with a tarp on the roof wants to wait.
SBA has been working on the speed problem from its end. A recent interim final rule preempts state and local requirements that were delaying the repair, rehabilitation, and replacement of property financed with SBA disaster loans, and the rule is framed around getting families and businesses back into repaired property faster. That helps once the loan funds. The inspection and the underwriting review still come first, and that's the gap home equity fills.
Where Home Equity Fits
Home equity comes in two shapes. A home equity loan gives you a lump sum at a fixed rate with a fixed payment. A HELOC gives you a line you draw against as the bills come in, usually at a variable rate. Which one fits your situation is a conversation to have with your loan officer, and the order I lay out in this article works with either. What both share is the part that matters after a storm: they're underwritten on your credit, your income, and the equity in the home, and they move on a lender's timeline rather than a federal agency's.
That timeline has one built-in pause worth knowing about. Under Regulation Z, a HELOC secured by your principal residence carries a right to cancel for three business days after the account opens or after you receive the account-opening disclosures, whichever comes later. The CFPB's guidance on it is simple: notify the lender in writing inside that window and every fee you paid gets refunded. It's a consumer protection, and it's also three business days before you can put the money to work, so build it into your plan. A closed-end home equity loan on your principal residence carries the same three-business-day right, so the pause is there whichever product you choose.
Now the price. There's no weekly government survey of home equity rates the way Freddie Mac publishes one for first mortgages, so I'll give you the two benchmarks that anchor it and let your own quote fill in the rest. A variable-rate HELOC is priced off the bank prime loan rate plus a margin your lender sets, and the Federal Reserve's most recent weekly release put prime at 7.00%. For backdrop, the 30-year fixed mortgage averaged 7.40% in Freddie Mac's latest survey, and a second lien typically prices above a first. Set either of those next to SBA's 4% and 8% ceilings and the gap is obvious. Home equity costs more. You're paying for speed, and after a storm, speed has real value.
| What you compare | SBA home disaster loan | Home equity loan or HELOC |
|---|---|---|
| Rate | Fixed, capped by regulation at 4% or 8% depending on SBA's credit-elsewhere finding | Your lender's quote; HELOCs float at prime plus a margin, home equity loans are usually fixed |
| Speed | After FEMA referral, SBA inspection, and underwriting review | Lender's timeline, plus a three-business-day cancellation window |
| First payment | Deferred 12 months, no interest in the deferral | Starts on the normal schedule after you draw or close |
| Term | Up to 30 years | Set by your agreement; HELOC draw period then repayment period |
| Collateral | Lien on the home above $50,000 in a Presidential declaration or $14,000 in an SBA declaration | Second lien on the home from day one |
| Prepayment penalty | None | Check the agreement for early-closure or paydown fees |
| Who decides | SBA, tied to a disaster declaration | Your lender, on your credit, income, and equity |
If you're working with an AmeriSave loan officer on the equity side, ask for the payment at a couple of different draw amounts, and ask whether the line carries an early-closure fee. You're going to want to pay this balance down fast, and you want to know the cost of doing that before you sign.
The $60,000 Roof, Three Ways
Take a repair bill that's common after a hurricane: $60,000 for a new roof and the interior damage the old one let in, none of it covered, in a county under a Presidential declaration. You have equity in the house. Three ways to pay for it. I'll keep the SBA math at the regulatory ceilings and leave the home equity rate as whatever your lender quotes, since I won't put a made-up number in your head.
Home Equity Alone
You apply, close, wait out the three-business-day cancellation window, and draw $60,000. The roof gets started as soon as the contractor can get there. Interest starts the day you draw and runs at your quoted rate, prime plus margin on a HELOC or a fixed second-lien rate on a loan, for as long as the balance sits there. This is the fastest start of the three and the most expensive way to carry $60,000 over the long run. It also leaves federal help on the table. Skip the SBA application and you give up two things: the FEMA referral a declination would have triggered, and the chance to find out whether you qualified for money at a fraction of the cost.
SBA Alone
You register with FEMA, get referred, apply, and wait for the inspection and the underwriting review. If approved, you borrow $60,000 at a fixed rate no higher than 4% or 8% depending on SBA's credit-elsewhere finding. The payment at those ceilings is about $286 or $440 a month over 30 years, your first payment is a year out, and no interest accrues in that first year. It's the cheapest money in this article by a wide margin.
The cost is time. Until SBA inspects, approves, and disburses, the roof stays open. If your contractor needs a deposit to hold your slot, you need cash before the SBA money arrives. And if SBA declines you, you've spent that waiting period with no repairs started, and you're now beginning the equity process from a standing start with a house in worse shape than when you began.
Equity Now, SBA Pays It Down
Day one, you do both. You register with FEMA and file the SBA application, and you call your equity lender the same afternoon. Once the line is open and the cancellation window has passed, you draw the $60,000 and the roof goes on. You carry that balance while SBA works. For planning, I'll call the bridge three months. Three months is my planning assumption. I haven't seen an official SBA timeline, so I won't quote one.
What does the bridge cost? At the prime rate alone, 7.00%, with no margin at all, three months of interest on $60,000 comes to about $1,050, and that figure is illustrative. Your line will carry a margin on top of prime, so treat $1,050 as the floor, with your margin adding to it. Against a $60,000 repair that's already underway, that's the price of a dry house.
When SBA funds, you use the proceeds to pay the equity balance down. From that point you're carrying $60,000 at no more than 4% or 8%, whichever tier SBA's credit-elsewhere finding put you in, with the first SBA payment a year out, no interest in the meantime, and no prepayment penalty if you decide to clear it early. The equity line goes back to zero and stays open for the next thing life sends your way.
Two checks before you count on this. First, ask your SBA loan specialist, before you draw, how the repairs you're paying for from the line match the repairs on your SBA application, and keep every invoice, photo, and adjuster letter in one folder. Second, read your equity agreement for any early-closure or paydown fee, because taking a line down to zero inside a few months is exactly what this plan does.
And if SBA says no? You're already repairing the house, and the declination letter is your referral back to FEMA for Other Needs Assistance. You kept every option open by filing first.
Apply for Both on Day One
The rule is short: apply for both on day one. The steps behind it are worth spelling out, because the order inside day one matters too.
- Register with FEMA for disaster assistance. This is the front door, and it's how you get referred to SBA.
- Complete the SBA application as soon as the referral comes, whether or not you expect to be approved and whether or not you want the loan. A declination unlocks the FEMA grant review. An approval leaves you free to decline.
- Call your equity lender the same day. If you already have a line, confirm what's available to draw. If you don't, start the application and be upfront about the storm damage. The lender is going to ask about the condition of the house, and that conversation goes better when you raise it first.
- Tell each lender about the other. SBA will want a lien if the loan is over the collateral threshold, and your equity lender needs to know a federal lien may be recorded behind it. Nobody likes learning about another lien at the closing table.
- Keep the paper. Insurance denial letters, adjuster reports, contractor estimates, and receipts go in one place, because FEMA, SBA, and your equity lender will each ask for some of it.
If you're reading this before a storm rather than after one, the cleanest version of this plan is a line that's already open. A HELOC you never draw on is ready the day you need it, and it turns step three into a phone call rather than a new application on a damaged house. If you're not sure whether a standby line makes sense for your situation, that's a short conversation with an AmeriSave loan officer, and it's a much easier one to have in a dry month.
What I'd Want You Comfortable With Before You Sign Either One
Earlier in my career, the borrowers who came through a hard stretch in the best shape had one thing in common. They didn't let urgency pick the lender for them. A storm compresses your timeline. It shouldn't compress your questions.
On the equity side, ask about the fees to open the line and for the payment broken down into principal and interest at the draw amount you expect. Find out whether the rate is fixed or variable, and if it's variable, what index and margin it follows. And get a straight answer on what it costs to pay the balance down to zero within a few months, since that's the plan.
A good lender shows you more than one way to structure this. If the only thing on the table is a single number with pressure to sign today, that's a signal, and it's the same signal whether the person across from you is a lender or a contractor. At AmeriSave, our loan officers walk through options without anyone rushing you, and a storm doesn't change that standard.
On the SBA side, the questions are different: which rate tier SBA placed you in and why, what collateral it's taking and where its lien will sit, and how and when the money gets disbursed. Asking them is part of being comfortable with the loan rather than just relieved to have it.
The comfort test matters more after a disaster than at any other point in homeownership, because the pressure to say yes to the first available dollar is at its highest. Slow down enough to ask. Then move fast on the answer.
The Bottom Line
I can't tell you when the next storm comes, and I won't guess what rates do between now and then. What I can tell you is what doesn't change. Cheap money is slow and fast money costs more, and after a disaster you need both. The SBA home disaster loan carries the repair for the long haul at a rate capped by regulation, with a year before the first payment and no penalty for paying early. Home equity gets the roof on this month. The order you use them in is yours to decide, and the order that holds up is equity first, SBA second.
Apply for both on day one, and start the repairs with the money that shows up first. Let the cheaper loan take over when it arrives. If SBA says no, you've lost nothing but a form, and the declination sends you back to FEMA for grant review. If you'd like to talk through the equity side of that plan, an AmeriSave loan officer can walk you through the options and the numbers at whatever pace you're comfortable with.
U.S. Small Business Administration. Physical damage loans.
U.S. Government Publishing Office. 13 CFR 123.104, What interest rate will I pay on my home disaster loan?
Federal Emergency Management Agency. FEMA Assistance and SBA Loans.
Federal Emergency Management Agency. Submitting SBA Application May Lead to Additional Disaster Assistance.
Consumer Financial Protection Bureau. I wanted to take out a home equity line of credit but my lender told me the terms have changed. What can I do?
Freddie Mac. Primary Mortgage Market Survey.
Board of Governors of the Federal Reserve System. H.15 Selected Interest Rates.
Federal Register. Improving SBA Disaster Loan Ability To Provide Meaningful and Timely Assistance.

Carl leads sales operations at AmeriSave, where he has served since August 2015. He holds a BBA in Business Administration & Management from the University of Kentucky and previously served as Director of Sales at Discover Financial Services. Based in Louisville, KY with his family, Carl brings a practical, solution-focused approach to mortgage sales that emphasizes transparency and reducing buyer anxiety.
Frequently Asked Questions
Yes. The Small Business Administration's disaster loan program covers homeowners and renters, and FEMA's guidance on the program says directly that you don't need to own a business to apply. As a homeowner in a declared disaster area you can borrow up to $500,000 to repair or replace your primary residence and up to $100,000 to replace personal property such as furniture, clothing, and a vehicle. The usual path in is registering with FEMA for disaster assistance and being referred to SBA. If SBA approves you, you're free to turn the loan down, and if SBA declines you, the declination sends you back to FEMA for consideration under Other Needs Assistance.
Your home has to sit in an area covered by a Presidential disaster declaration or an SBA administrative declaration, and the damage has to be to your primary residence or your personal property. You submit an application, SBA inspects the damage and reviews your credit, and it decides whether you could get credit elsewhere, which sets your rate ceiling at 4% or 8%. Above $50,000 in a Presidential declaration, or $14,000 in an administrative one, SBA asks for collateral to the extent you have it and prefers real estate, though it won't decline you solely for lacking collateral. Ask your SBA loan specialist directly about credit standards for your disaster.
Use both, in order, if you can. The SBA loan is cheaper by regulation. Its fixed rate is capped at 4% if SBA finds you can't get credit elsewhere, or 8% if it finds you can, and you get a year before the first payment with no interest accruing during that year. It funds only after an inspection and underwriting review. A HELOC or home equity loan closes on a lender's timeline and lets you start repairs while SBA works, at a rate that runs well above SBA's ceilings. Draw on the equity to start the roof, then use the SBA proceeds to pay that balance down once the loan funds. Before you draw, confirm with SBA how the repairs match your application and check your line for early-closure fees.
A denial sends you back to FEMA. FEMA's fact sheet on the subject says that if SBA declines your loan, SBA refers you to FEMA and you may be eligible for additional grant assistance under Other Needs Assistance, which covers needs like personal property and transportation. That referral only happens if you completed and submitted the SBA application, which is why FEMA tells applicants to finish it even when they expect a no or don't want a loan. If you've already opened a home equity line and started repairs, the denial leaves the work underway and shifts the long-run financing question to your equity lender and to FEMA's grant review.
No for the SBA loan, and it depends on the agreement for the HELOC. SBA's program page states there's no prepayment penalty on a disaster loan, so if your finances improve or an insurance appeal comes through later, you can pay it down without an added charge. On the HELOC or home equity loan side, some lines carry an early-closure fee if you close the account within a set period after opening, and some home equity loans carry prepayment terms of their own, so read the agreement and ask your loan officer before you sign. Since the plan in this article pays the equity balance down within months, that answer matters more than usual.